
RBI’s Monetary Policy Review
On October 07, 2026, RBI’s Monetary Policy Committee (MPC) made following policy decisions:
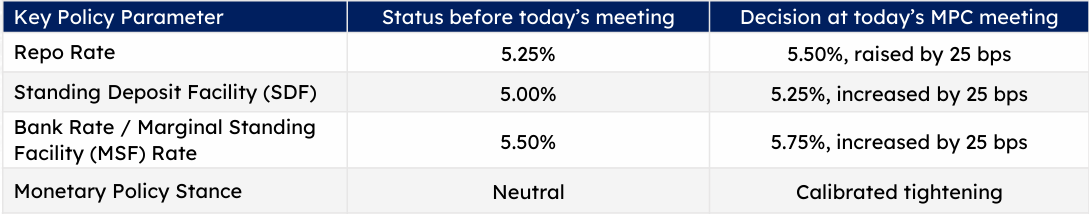
The RBI’s MPC voted unanimously to raise the repo rate by 25 bps to 5.50%. The MPC also decided to change the stance to calibrated tightening with a vote of 4:2.
Executive summary of RBI’s press releases/ press conference:
Global Economy:
• The re-escalation of the conflict in West Asia and the consequent sharp volatility in crude oil prices has kept the global economy in a state of flux
• Global growth has remained resilient. Acceleration of inflation in key economies has prompted a shift towards hawkish monetary policy
• Increasing inflation has caused major central banks to remain hawkish (US Fed hiked by 25 bps in September), while others remain watchful as global yields remain high
• West Asia conflict remains unresolved, keeping the crude oil volatile, global yields high indicating further tightening of global financial conditions
Domestic Growth:
• Despite global uncertainty, India’s domestic economic activity remained resilient as indicated by 7.8% Q1FY27 GDP growth and other high frequency indicators in Q2FY27
• The global headwinds will continue to affect the domestic economic activity. Private consumption, fixed investment and exports remained strong. Manufacturing and services stayed buoyant
• Weak monsoon may impact rural consumption, but healthy buffer of foodgrains and policy support should help contain the impact
• Urban consumption should stay supported by strong services momentum and stable employment conditions
• Investment activity should continue on the back of strong capacity utilization, healthy credit growth and government focus on infrastructure
• Real GDP growth projection for FY27 is raised by 40 bps to 7.1% from 6.7%. Overall risks to growth are evenly balanced
Source: RBI
Domestic Inflation:
• CPI inflation rose to 4.82% in August 2026 due to higher food and energy prices
• El Niño continues to pose a major risk due to its impact on rainfall distribution
• However, proactive supply management and adequate foodgrain stocks provide some comfort
• Global oil prices remain highly volatile due to geopolitical events, making the near-term outlook uncertain
• While overall inflation pressures are still moderate, there is a risk that higher food, fuel and input prices could spill over into broader inflation
• CPI inflation projection for FY27 is raised by 20 bps to 5.2% from 5.0%
Liquidity and Financial Market Conditions:
• Banking system liquidity increased to an average daily surplus of INR 5.9 lakh cr since August 2026 MPC meeting
• Liquidity in the banking system moderated in September 2026 due to Open Market Operation (OMO) Sales and Variable Rate Reverse Repo (VRRR) Operation by RBI, advance tax and GST outflows
• Short-term money market rates, especially CP and CD rates, softened in September
• RBI will continue using a mix of tools to ensure adequate liquidity in the banking system
• The aim will be to keep the weighted average call rate aligned with the policy repo rate
Outlook:
• In line with our expectations, MPC began its rate hiking cycle today. The RBI’s overall tone of the policy commentary was hawkish. Upward revisions to Growth (FY27 projection at 7.1%) and Inflation (FY27 projection at 5.2%) figures were also on expected lines
• In our view, RBI will hike rates by another 50-75 bps over the coming meetings. We expect RBI to undertake back-to-back hikes in upcoming MPC meetings rather than a staggered approach
• Continued West Asia conflict, inflation risks and weak monsoon impact may call for a longer and higher rate hike cycle
• Moreover, the stance was changed to calibrated tightening signaling that today’s decision is start of a rate hike cycle and not an isolated hike. It also gives RBI room to stay data dependent
• RBI will continue to absorb excess liquidity through Forex Sell/Buy swaps, VRRR, OMO sales (if necessary) but a Cash Reserve Ratio (CRR) hike would be the least preferred option
Source: RBI


 2026 HDFC TRU